Compare / Charlie Munger vs Bill Nygren
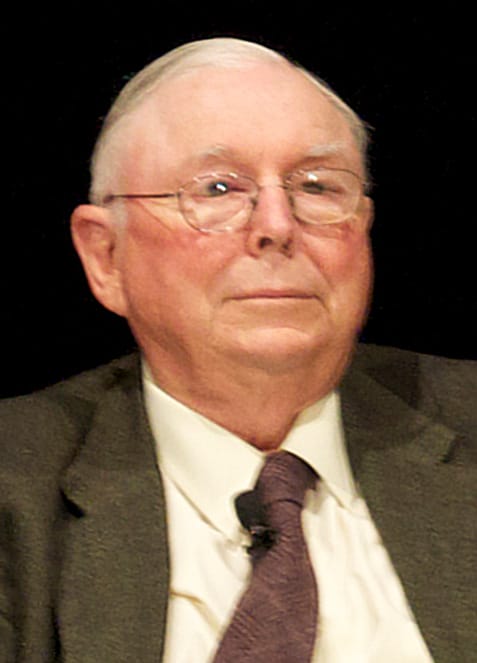
NETFIGO SCORE BATTLE
ORIGINAL DATARisk Appetite
Contrarian Index
Track Record
Accessibility
Time Horizon
AT A GLANCE
INVESTING STYLE
Charlie Munger
Munger's whole thing is mental models. The idea is simple: instead of being an expert in one field, you learn the core concepts from as many different fields as possible — psychology, biology, physics, economics, history — and then use that whole toolkit to think about problems.
He calls it a latticework of mental models. It sounds like a self-help concept.
It's actually how he consistently made better decisions than almost everyone around him. On investing, he pushed Buffett away from his old mentor's approach — which was basically "find dirt-cheap companies and flip them fast" — toward something more durable: find the best businesses in the world and hold them forever.
The key word he uses is moat. A business so dominant that competitors can't touch it.
Think Coca-Cola. He was also deeply influenced by psychology, particularly the ways humans reliably fool themselves.
He gave a famous talk called "The Psychology of Human Misjudgment" listing 25 ways our brains get things wrong. Reading it once will change how you make decisions.
Bill Nygren
Classic large-cap value. Nygren buys businesses trading significantly below his estimate of intrinsic value — typically at least a 40% discount.
He focuses on companies with strong management teams, high free cash flow generation, and the ability to allocate capital intelligently. He runs concentrated portfolios (20-30 stocks) and is willing to hold positions for 3-5+ years.
He is a contrarian by default — his best ideas are usually in sectors the market hates.
FINANCIAL PHILOSOPHY
Charlie Munger
Invert. Always invert.
That's his most famous rule — borrowed from the mathematician Jacobi. Instead of asking "how do I succeed?" ask "what would guarantee failure, and then avoid those things." It sounds obvious.
Almost nobody actually does it. He believes the secret to a good life and good investing is the same: figure out what you want to avoid, avoid it relentlessly, and most good things follow.
On wealth: getting rich isn't the hard part — keeping it is. Most people blow up by using borrowed money, getting greedy at the top, or panicking at the bottom.
Don't do those things. On decisions: only make the big bet when you're very sure.
Be patient for a long time, then move fast when the opportunity is obvious.
Bill Nygren
Nygren believes the market is generally efficient but occasionally misprices individual businesses, especially during periods of fear or sector-wide pessimism. He thinks like a business buyer, not a stock trader — asking "what would a rational private buyer pay for this entire company?" He considers management quality and skill at investing company money as important as the financial statements.
RISK TOLERANCE
Charlie Munger
Munger's approach to risk: don't take risks you don't understand, and don't take risks you don't need to. He kept things simple.
He concentrated into a small number of businesses he understood deeply. He used borrowed money only a handful of times in his whole life, and said so plainly — his own partnership fell by more than half in 1973-74 partly because of it.
He kept large cash reserves. His view on diversification was almost the opposite of what most financial advisors tell you — he thought spreading money across 50 stocks was an admission that you hadn't done enough homework.
If you've done the work, you concentrate. If you haven't, maybe don't invest at all.
Bill Nygren
Moderate. Nygren runs concentrated portfolios which adds stock-specific risk, but he focuses on large-cap, established businesses with strong balance sheets.
He is not swinging at biotech startups or crypto. The risk is being early and looking wrong for extended periods while waiting for the market to recognize value.
THE PLAYBOOK
Charlie Munger
Munger lived in the same house in Los Angeles for most of his adult life. He was famously frugal — not in a miserable way, but in a "I genuinely don't care about most things money buys" way.
He flew commercial until fairly recently. He read obsessively.
He described himself as a book with legs. His children joked that he was more interesting to talk to than almost anyone alive, but would only engage on topics he found intellectually stimulating.
He donated massively to education — hundreds of millions to the University of Michigan, UC Santa Barbara, Stanford and other institutions, often with very specific conditions attached. He designed buildings as a hobby and funded their construction himself.
He died at 99 worth around $2.6 billion — extraordinary by any measure, and somehow modest given he sat next to one of the richest men in history for 45 years.
Bill Nygren
Low-profile lifestyle. Based in Chicago.
Nygren does not seek media attention and rarely appears on financial TV. He writes detailed quarterly commentaries for Oakmark shareholders that are some of the best free investing education available.
He lets his long-term performance record speak for itself.
BIGGEST WIN
Charlie Munger
See's Candies. In 1972, Munger convinced a reluctant Buffett to pay what seemed like an expensive price — $25 million — for a California candy company.
Buffett thought it was too much. Munger held firm.
See's has since generated over $2 billion in profit for Berkshire, basically funding dozens of other acquisitions. It also taught Buffett the single most important lesson of his career: paying a fair price for a great business beats getting a cheap price for a mediocre one.
That one deal changed the entire direction of Berkshire Hathaway.
Bill Nygren
His consistency over nearly three decades. While many value managers have stumbled during the growth-dominated 2010s, Nygren adapted his approach to include "modern value" — companies like Alphabet and Meta that trade at low multiples relative to their growth rates.
His willingness to evolve his definition of value without abandoning the discipline has kept Oakmark relevant.
BIGGEST MISTAKE
Charlie Munger
Munger is famous for avoiding mistakes more than for making spectacular wins — his whole philosophy is about not doing stupid things. But he's admitted to a few.
He said Berkshire was too slow to move into BYD, China's electric vehicle company, despite knowing it was exceptional for years before they finally bought in. He also held too much Wesco Financial for too long when the money could have been put to better use elsewhere.
His most honest self-criticism: he wished he had moved faster when the evidence was already clear. For a man who spent his career warning others about psychological biases, he wasn't immune to them.
Bill Nygren
Holding financial stocks through the 2008 financial crisis. Oakmark Fund was down significantly in 2008 as bank and insurance stocks cratered.
While the long-term recovery proved him right on many of those holdings, the drawdown was painful for investors who redeemed at the bottom.
CAREER HIGHLIGHTS
Charlie Munger
Charlie Munger grew up in Omaha — same city as Buffett, but they didn't know each other yet. His father was a lawyer.
So was his grandfather. Charlie became one too, but he was clearly more interested in figuring out how the world worked than in courtrooms.
He studied math at the University of Michigan, got drafted into World War II, trained as a meteorologist, and somehow ended up at Harvard Law School without ever finishing an undergraduate degree. Harvard took him anyway.
He graduated in 1948 and moved to California to practice law. He was good at it.
He was also quietly building a real estate business on the side that made him more money than law ever did. He and Buffett met at a dinner in Omaha in 1959.
Munger was 35. Buffett was 28.
By the end of the night, Buffett was trying to convince Munger to go into investing full time. It took about a decade.
Munger ran his own investment partnership from 1962 to 1975 — returned 24% annually while the market did 6.4%. Then he fully merged his career with Buffett's at Berkshire, where he stayed until his death in 2023.
Bill Nygren
Joined Harris Associates (parent of Oakmark Funds) in 1983. Became lead portfolio manager of the Oakmark Fund in 2000.
Lead manager of Oakmark Select Fund since 1996 and Oakmark Global Select since 2006. Oakmark Select Fund has returned over 11% annually since 1996 inception.
Manages over $20 billion across Oakmark strategies. Named Morningstar Domestic Stock Fund Manager of the Year in 2001.
Known for buying out-of-favor large-cap value stocks and holding them for years. Has consistently argued that the market overreacts to short-term problems and undervalues franchises with durable competitive advantages.
COMPANIES & ROLES
Charlie Munger
Munger's main stage was Berkshire Hathaway, where he served as Vice Chairman from 1978 until he died. His role was hard to define on paper — he didn't run a fund or manage a portfolio.
What he actually did was talk to Buffett. That was worth a trillion dollars.
Before Berkshire, he ran his own investment partnership from 1962 to 1975 that crushed the market. He also controlled Wesco Financial, a small insurance and financial company he ran as a personal Berkshire subsidiary from 1973 to 2011, until Berkshire fully absorbed it.
Outside finance, he was obsessed with architecture — he personally designed several buildings, including the graduate residence he funded at the University of Michigan. His proposed Munger Hall at UC Santa Barbara went the other way.
It gave 94% of its bedrooms no windows, an architect on the review committee resigned in protest in 2021, and the project was eventually abandoned.
Bill Nygren
Oakmark Funds (lead portfolio manager), Harris Associates (partner)
EDUCATION
Charlie Munger
University of Michigan, mathematics — left for World War II without graduating. US Army Air Corps, meteorology training.
Harvard Law School, JD 1948 — admitted without an undergraduate degree, which Harvard is apparently capable of when it wants to be.
Bill Nygren
CFA charterholder. MBA from the University of Wisconsin-Madison.
Undergraduate degree from the University of Minnesota. Has spent his entire career at Harris Associates — over 40 years at one firm.
BOOKS & RESOURCES
Charlie Munger
Munger endorses it, Buffett calls it the best investing book ever written, and they're both right
Munger recommended this for years as the best book on human psychology. He believed understanding psychological biases was essential to investing
Written as a synthesis of Munger's thinking, often recommended by Munger himself
As an Amazon Associate, Netfigo earns from qualifying purchases. Book links above may be affiliate links.
Bill Nygren
Nygren's own quarterly Oakmark commentaries are worth reading. He frequently cites Warren Buffett and Charlie Munger as influences
As an Amazon Associate, Netfigo earns from qualifying purchases. Book links above may be affiliate links.